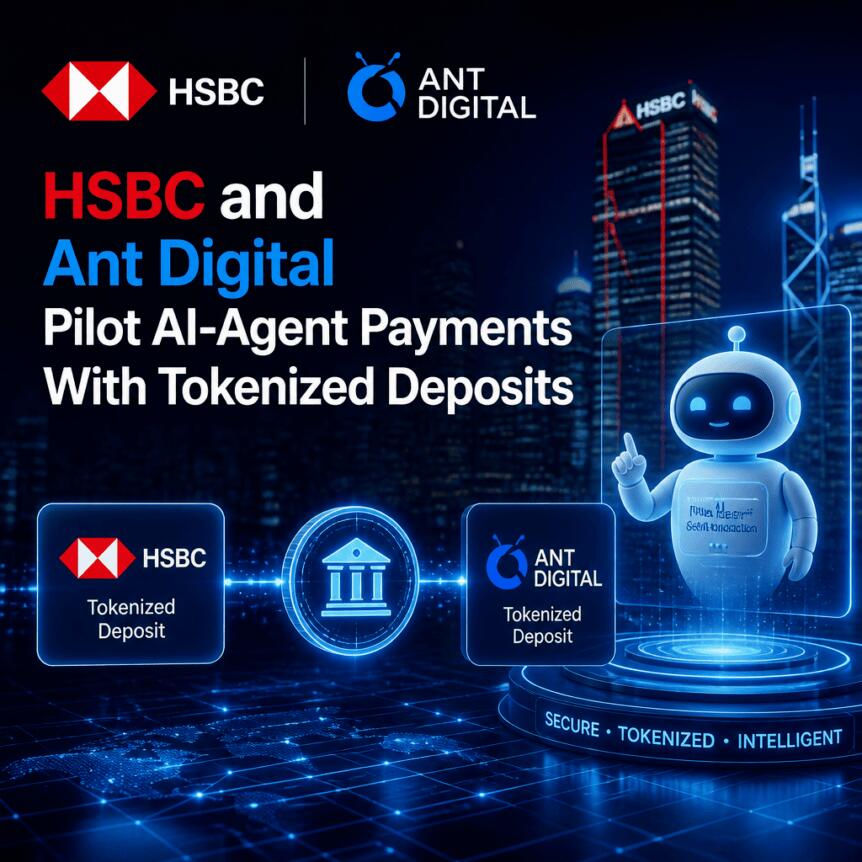
HSBC and Ant Digital Technologies say they have successfully tested an AI-agent payment workflow that uses tokenized bank deposits, with settlement occurring in real time on a blockchain test environment. The demonstration combined HSBC’s Tokenised Deposit Service with Ant Digital’s Anvita Flow network for AI-driven service access and payments, using Jovay Testnet as the layer-2 testing platform.
In the test, a simulated AI agent selected a digital service and completed a payment described by the companies as a micropayment—typically defined as transfers under $2. HSBC handled settlement and real-time risk checks, while Ant Digital’s system coordinated how the agent found the service and executed the payment.
Key takeaways
- HSBC and Ant Digital demonstrated an AI-agent payment flow tied to tokenized deposits, settled on a blockchain testnet in real time.
- Both firms emphasized technical verification rather than a commercial product or live customer offering.
- Risk controls were part of the demo: HSBC included real-time risk checks alongside settlement.
- Micropayments were central to the experiment, aligning with use cases where AI agents may make frequent small purchases.
- The test fits a broader trend of banks experimenting with agent-initiated payments using payment infrastructures and programmable rails.
What HSBC and Ant Digital tested
According to the announcement made Friday, the trial was designed to validate how AI agents could interact with financial services and execute payments without manual steps in the middle of the process. The architecture paired service discovery and execution (via Ant Digital’s Anvita Flow) with tokenized deposit settlement (through HSBC’s Tokenised Deposit Service).
The transaction path relied on Jovay Testnet, a layer-2 blockchain testing environment where settlement could be checked under near-production conditions. The companies’ focus on “real-time” settlement suggests the workflow was meant to mimic how quickly an agent might need to pay when a service is selected—particularly relevant for micropayments, where speed and automation are often more important than traditional batch settlement cycles.
While the companies did not frame the demo as a full product deployment, the inclusion of real-time risk checks is notable for investors and builders. In agent-driven finance, payment execution must be coupled with compliance and controls that can scale as transactions become more frequent and occur in more contexts.
Not a launch—only a verification step
HSBC and Ant Digital explicitly stated that the exercise was limited to technical verification. The companies said it does not represent a commercial launch or an offering available to live customers.
For market participants, that distinction matters. Bank-linked tokenization and blockchain settlement proposals often get evaluated on two dimensions: whether transactions can be executed successfully end-to-end, and whether the workflow can operate safely with real risk management and compliance. This test appears to target the first dimension—technical feasibility—while highlighting that risk checks were integrated into the settlement stage.
What remains unclear is how the approach would scale beyond a controlled demonstration: whether additional safeguards, auditing, and operational controls would be needed for broader service categories, higher transaction volumes, or more complex customer approval flows.
A wider push toward AI-agent payments
This HSBC-Ant Digital experiment joins a growing set of bank and payment-industry trials exploring how AI agents could initiate transactions.
In March, Santander completed a controlled end-to-end payment test using Mastercard’s Agent Pay infrastructure, executed via the bank’s live payment systems. In May, Sygnum reported its own test for AI-agent-driven digital asset transactions on a blockchain mainnet, with customers required to approve and sign each transaction. Also in May, CaixaBank completed an AI-agent-initiated card transaction using Visa Intelligent Commerce and existing merchant payment systems.
Taken together, these efforts highlight different technical paths to similar end goals: enable AI agents to request and execute payments while preserving some level of customer consent and institutional controls. The HSBC test appears focused on tokenized deposits and blockchain settlement performance, while other trials have leaned more on established payment rails integrated with agent tooling.
The debate: can incumbents adapt to always-on agents?
Even with multiple high-profile demonstrations, skepticism remains about whether traditional banks can quickly adapt core infrastructure for AI-driven finance.
In a May interview with Cointelegraph, Augustus Bank CEO Ferdinand Dabitz argued that incumbents cannot simply rebuild on decades-old systems designed for human-operated workflows rather than automated, around-the-clock transaction processing. He suggested that clearing and settlement infrastructures were not originally built for continuous execution driven by software agents.
Augustus, the interview indicated, is working on a US bank model oriented around stablecoins and AI-driven operations—an approach that effectively assumes the fastest path to agent-native finance may require purpose-built rails rather than retrofits.
This tension—between incremental trials using existing banking structures and the push for new agent-first architectures—may be one of the defining themes in the next phase of adoption. HSBC’s demonstration suggests banks can experiment with tokenization and risk checks alongside agent workflows, but it does not settle whether such systems can scale efficiently enough to meet the demands of fully automated payments.
Why programmable payments could matter for blockchain adoption
Beyond banking experiments, an investment research view recently emphasized the link between AI agents and the need for infrastructure that can run continuously and execute logic programmatically.
In an Oct. 8 report titled Breaking The Wall, Citrini Research argued that autonomous agents could expand demand for programmable financial systems. The firm’s core thesis was that traditional financial setups—built primarily around human users—may need to evolve as agents increasingly manage transactions across applications. It suggested that blockchain networks can provide always-on rails for moving money and financial assets.
“AI agents move programmatically, 24/7, across applications, and it’s only logical that money and financial assets eventually will, too,” Citrini wrote.
HSBC and Ant Digital’s test fits that narrative from a practical angle: it centers on real-time settlement tied to tokenized deposits and controlled payment execution by an AI agent. Still, the path from a technical demo to widespread adoption depends on more than settlement speed—it also hinges on operational integration, customer experience, compliance, and the ability to manage risk across diverse transaction types.
Next, investors and users should watch whether these experiments progress into broader pilots that include more complex service categories, clearer customer consent mechanisms, and measurable performance under higher transaction loads—especially if banks aim to support the “always-on” payment cadence that AI agents imply.