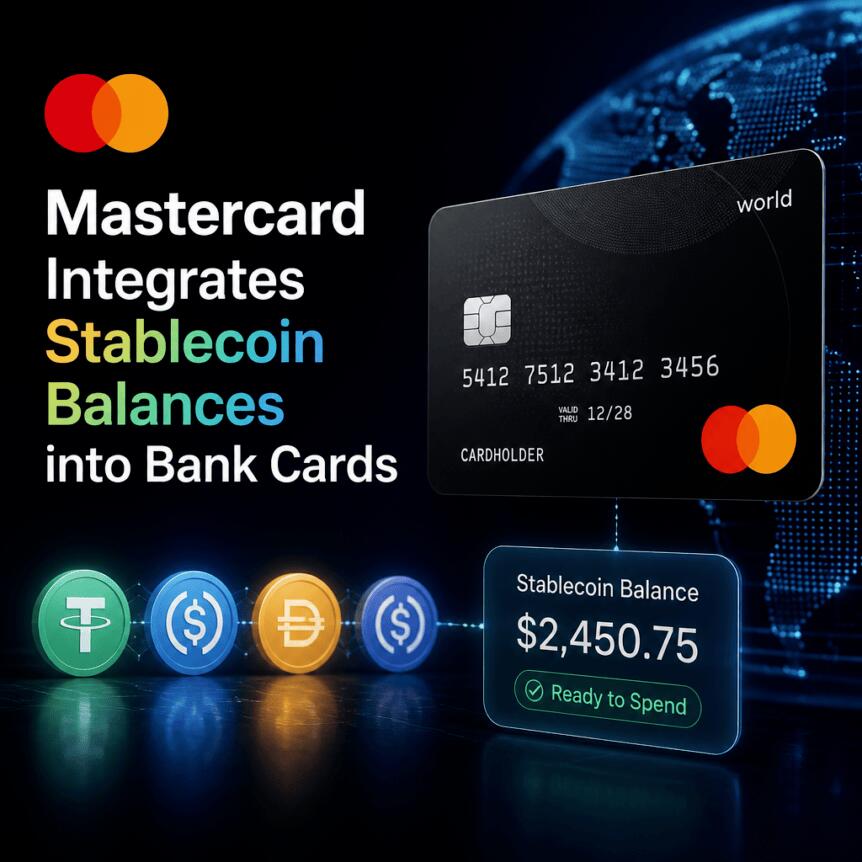
Mastercard has unveiled a new stablecoin-focused payments platform aimed at making it easier for businesses and financial institutions to offer stablecoin services without having to build their own payment and conversion infrastructure from scratch.
Announced this week, the platform—called Global Money Platform—is Mastercard’s first major integration with BVNK, the stablecoin infrastructure company Mastercard acquired in August. The move signals that stablecoin payments are moving beyond pilots and into “pluggable” infrastructure that traditional finance providers can deploy under their own branding.
Key takeaways
- Mastercard’s new Global Money Platform is designed to help businesses hold and convert fiat and stablecoins alongside traditional banking and card services.
- The service links stablecoin balances to Mastercard’s ecosystem, including payments routed through its Move network and spend via its merchant card network.
- Mastercard says the platform can enable stablecoin-linked cards and payments into recipients’ local bank accounts.
- Partnerships with fintech firms such as Nuvei and Marqeta are included among the early integration partners.
- The launch places Mastercard closer to Visa’s stablecoin platform strategy, which was announced earlier this year.
Global Money Platform: stablecoins inside familiar rails
At the core of Mastercard’s announcement is a framework that connects stablecoin functionality to existing payment workflows. According to Mastercard, businesses using the platform can:
- Hold and convert fiat currencies and stablecoins, enabling smoother movement between traditional money and digital assets.
- Issue stablecoin-linked cards, allowing cardholders to spend with stablecoin balances.
- Make payments from stablecoin balances that are delivered to recipients through local bank accounts.
This matters because it reframes stablecoin use from a standalone crypto activity into an interoperable component of mainstream payments. Instead of requiring every provider to design stablecoin custody, conversion, and payment routing themselves, the pitch is that Mastercard can supply a ready-made set of building blocks.
How the platform routes payments and enables card spending
Mastercard says the Global Money Platform ties into its Mastercard Move network, which can route payments to “more than 17 billion destinations,” including bank accounts and cards.
It also describes a second connection: stablecoin balances can be linked to Mastercard’s merchant ecosystem so customers can spend via payment cards. In practical terms, this creates a pathway where stablecoins can be used both for settlement-like transfers and for day-to-day purchases—two use cases that often require different payment plumbing.
Mastercard did not position this as a consumer wallet product. Instead, it appears aimed at institutions and payments partners that want to embed stablecoin functionality into existing offerings such as cards, accounts, or remittance flows.
BVNK integration and the broader stablecoin push
The platform’s launch is closely tied to Mastercard’s acquisition of BVNK in August. Mastercard is presenting Global Money Platform as its first major integration with BVNK following that deal, indicating that the company is moving to turn acquisition-driven capabilities into externally usable infrastructure.
The company’s framing is also a strategic shift: Mastercard is not only processing payments, but providing an infrastructure layer other institutions can integrate. For investors and operators watching the stablecoin market, that distinction is important. When a major payments network offers a standardized route for stablecoin services, it can reduce friction for traditional players and potentially accelerate deployment across regions.
Early integration partners highlighted by Mastercard include Nuvei and Marqeta, among others, suggesting the company is aiming for a broader ecosystem rollout rather than a single deployment.
Competitive pressure: Mastercard moves into Visa’s stablecoin lane
Mastercard’s announcement also highlights competitive dynamics with Visa. Earlier in the year, Visa launched a stablecoin platform that allows financial institutions to hold, mint, and transfer stablecoins—an approach Mastercard’s new offering resembles from an outcome perspective.
While the details of each platform’s operational design are not fully comparable based on the information in Mastercard’s release alone, both companies are signaling that stablecoin infrastructure is becoming a core part of how major card networks may support digital asset rails.
For market participants, this competition could matter in two ways: first, it raises the likelihood that stablecoin-enabled card and payment offerings become more standardized; second, it may force institutions to evaluate not just the stablecoin asset itself, but the partner ecosystem that handles conversion, custody interfaces, and payment routing.
Stablecoin activity signals—and what remains uncertain
Mastercard’s push comes amid ongoing industry interest in stablecoin usage. The article references research from Standard Chartered suggesting stablecoin transaction activity is growing, even though circulating supplies of major tokens such as USDt and USDC have remained relatively flat this year.
This is a useful tension to understand. Stablecoin market narratives can often focus on supply growth, but activity metrics may diverge—meaning adoption can rise through turnover, settlement frequency, or payment conversion cycles even if total issuance does not move dramatically. Mastercard’s platform fits that framing by targeting real-world payment usage rather than increasing stablecoin supply on its own.
Still, readers should watch how quickly integrators adopt the platform and what specific stablecoin use cases expand first—card spending, bank transfers, or both. Another key question is how institutions will operationalize conversion and reconciliation for end users, since stablecoin integration typically requires careful alignment with compliance and reporting processes.
As stablecoin infrastructure becomes more “plug-and-play,” the next benchmark will be adoption pace: which institutions integrate Global Money Platform, how they package stablecoin services for customers, and whether usage scales across major corridors beyond early partners.