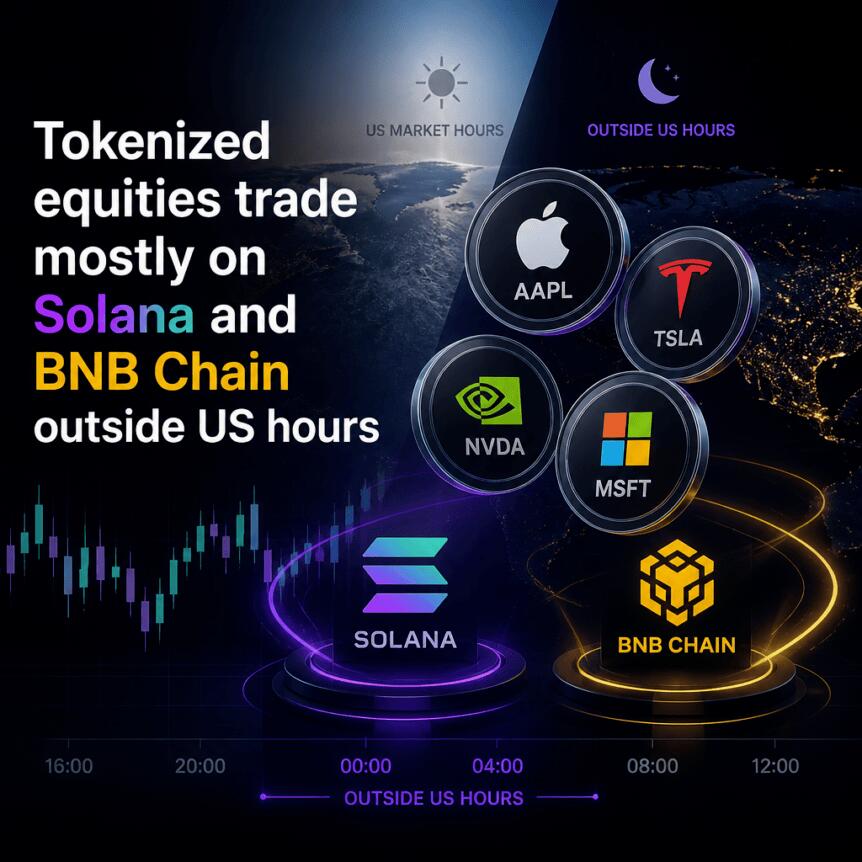
Trading tokenized stocks outside of traditional market hours is becoming the norm on several major blockchains, according to onchain volume data cited by The Kobeissi Letter. The pattern is a strong early signal that one of the core benefits of tokenizing equities may be enabling trading whenever markets on the other side of the Atlantic are closed.
Blockworks data highlighted by The Kobeissi Letter shows that on BNB Chain, more than 70% of tokenized stock trading volume takes place outside the standard 9:30 am to 4 pm Eastern session. The share is 63% on Solana and nearly 60% on Base, pointing to broad adoption of “always-on” trading among users of onchain equity products.
Key takeaways
- More than 70% of tokenized stock volume on BNB Chain occurs outside US regular trading hours, with 63% on Solana and nearly 60% on Base.
- The data suggests traders are using tokenized equities to access liquidity when traditional exchanges are closed, not just duplicating daytime activity.
- Solana-based Jupiter reported a 50% month-over-month increase in tokenized asset trading volume.
- Tokenized stock values rose 15% over 30 days to nearly $3.3 billion, according to RWA.xyz.
- Regulatory momentum is building: the SEC introduced an “innovation exemption” for venues looking to trade tokenized US-listed stocks on public blockchains.
Onchain trading shifts away from US market hours
The distribution of volume across time is where the story gets most interesting. If tokenized stocks were merely mirroring activity from US exchanges, you would expect most trading to cluster during regular market hours. Instead, the figures cited by The Kobeissi Letter indicate that a majority of trading happens after those windows close.
On BNB Chain, that outside-hours share exceeds 70%. On Solana and Base, the majority of activity also falls outside the 9:30 am to 4 pm Eastern timeframe—63% and nearly 60%, respectively. That means the “round-the-clock” promise of tokenization is not just theoretical; it appears to be reflected in user behavior.
This timing pattern matters for both traders and liquidity providers. For traders, always-on access can reduce the friction of waiting for the next US session to act. For market makers and liquidity operations on-chain, it changes expectations around when to deploy capital and where demand will show up.
Growth in tokenized equity volume and total value
The shift in trading hours is supported by broader growth signals. Jupiter, a major Solana-based trading platform, reported a 50% month-over-month increase in tokenized asset trading volume. While platform-level data doesn’t explain all users across all venues, it supports the idea that activity is expanding, not stagnating.
Meanwhile, RWA.xyz data indicates tokenized stock values have increased by 15% over the past 30 days to nearly $3.3 billion. The value is not concentrated in a single token issuer. The report attributes a significant portion of the ecosystem’s issuance and trading to companies including Ondo Global Markets, xStocks, and bStocks, with tokens issued and traded across different blockchains.
Taken together, these points suggest that the market for tokenized equities is both expanding in size and changing in usage patterns—moving toward after-hours engagement as a meaningful slice of overall volume.
What regulators are trying to enable in the US
The onchain market’s “outside-hours” behavior is arriving at a time when US regulators are beginning to address how tokenized equities could be handled within traditional market frameworks.
Last month, the Securities and Exchange Commission (SEC) introduced an “innovation exemption” that allows qualifying venues to trade tokenized US-listed stocks on public blockchains. According to the SEC-linked details described in coverage by Cointelegraph, participating venues must publish transaction data in US dollars, including trade prices, sizes, timestamps, and daily trading volumes. They must also disclose liquidity pool addresses and balances.
Commissioner Mark Uyeda also emphasized transparency requirements around transaction reporting and liquidity disclosure, reflecting the SEC’s focus on investor protections and market integrity as tokenized trading expands.
The exemption is also framed as a path that differs from existing tokenized stock products, such as xStocks and Ondo Global Markets, which are generally not available to US investors. In other words, while tokenized stock activity is already happening on-chain, the regulatory development aims to determine whether some venues can offer tokenized US equities domestically—provided they preserve shareholder rights and satisfy trading and disclosure requirements.
Why after-hours trading could become the real adoption driver
Tokenized equities have often been sold as a way to bring traditional assets on-chain. But the current volume pattern highlighted by Blockworks data suggests a different angle may be winning adoption: timing.
When a large share of trading occurs while US exchanges are closed, it implies investors are turning to tokenized stocks for practical execution. That could mean strategies that don’t fit neatly into the daily trading schedule—such as reacting to overnight developments, managing risk between sessions, or accessing liquidity across time zones.
At the same time, it’s not yet clear how much of this behavior will carry over once tokenized US equities become available through compliant venues under the SEC’s framework. The exemption introduces structural and disclosure requirements that could affect how liquidity is provisioned and how platforms operate. The key uncertainty for investors and builders is whether the “always-on” demand seen today will persist once new products become eligible in the US, and how quickly liquidity can scale under those rules.
For now, the most actionable takeaway is that tokenized equity usage appears to be evolving beyond daytime replication. As regulatory pathways open and platforms compete for liquidity, the next phase to watch is whether after-hours trading volumes—and the liquidity infrastructure behind them—continue to grow across more venues and jurisdictions.