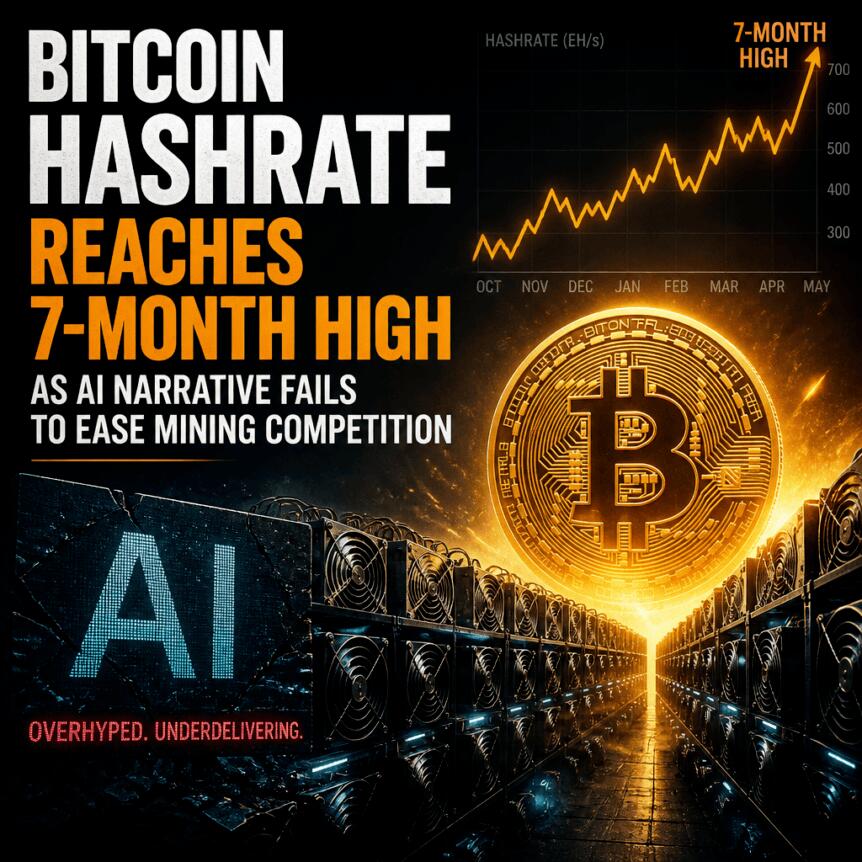
Bitcoin’s mining capacity has continued to bounce back, with network hashrate returning to levels last seen in early March—even as a wave of publicly traded miners reallocates computing resources toward artificial intelligence and other high-performance workloads.
According to BlocksBridge Consulting’s latest Miner Weekly newsletter, Bitcoin’s seven-day average hashrate has climbed back above 1 zettahash per second (ZH/s), equivalent to 1,000 exahashes per second (EH/s). That marks the highest point since March 3, a notable reversal for a network that has been absorbing major shifts in miner deployment.
Key takeaways
- BlocksBridge reports Bitcoin’s seven-day average hashrate has returned above 1 ZH/s (1,000 EH/s) for the first time since March 3.
- Bitcoin’s mining difficulty increased by 5.92% on Oct. 16, and BlocksBridge expects another 5.16% rise at the next adjustment.
- If BlocksBridge’s estimate holds, difficulty would be up about 11.4% across two consecutive adjustment cycles—leaving less “breathing room” for remaining miners.
- The hashrate recovery suggests displaced capacity from AI-related conversions is not disappearing entirely; it may be rerouted through smaller operators and secondhand hardware channels.
- Some market analysts interpret rising hashrate as an indirect bullish signal tied to continued institutional exposure to mining operators.
Hashrate back above 1 ZH/s despite AI-driven reallocation
Hashrate is the measure of computing power used to secure the Bitcoin network. In practical terms, a rising hashrate typically indicates that more machines are competing to solve the proof-of-work puzzle—raising the difficulty of earning rewards at a given set of network rules.
BlocksBridge’s latest snapshot argues that the network has not experienced lasting relief from the AI migration that has pulled capacity away from Bitcoin mining. The newsletter frames the renewed hashrate strength as evidence that “other operators are replacing lost computing power,” intensifying competition for the miners still producing blocks.
The backdrop is the industry’s ongoing pivot toward AI workloads. BlocksBridge previously reported that publicly traded miners saw a 23% decline in realized hashrate, alongside a 52% quarterly increase in reported AI and high-performance computing revenue. In the same assessment, it estimated the displaced mining hardware represented roughly $1.5 billion in equipment.
Difficulty is also rising—so margins may stay under pressure
Even if hashrate is recovering, the network’s adjustment mechanism determines how difficult it is to find blocks. BlocksBridge notes that Bitcoin’s mining difficulty rose by 5.92% on Oct. 16 and projects another 5.16% increase at the next difficulty change.
Under that projection, difficulty would climb roughly 11.4% over two consecutive adjustment periods. For miners that continue to operate on Bitcoin, higher difficulty generally means they need either more efficient equipment, lower electricity costs, or stronger operational execution to remain profitable—regardless of what other industry segments are doing.
BlocksBridge explicitly links this to expectations around the AI transition, suggesting miners may not be getting the “breathing room” some may have anticipated.
Where the missing power might be going: secondhand machines and smaller operators
One plausible explanation for the hashrate rebound is that some capacity displaced from AI conversions is returning to Bitcoin via different channels. BlocksBridge points to smaller and mid-sized miners acquiring equipment from larger operators, particularly where hosting and deployment infrastructure makes it easier to relocate machines quickly.
As an example, the newsletter highlights Sazmining, which markets secondhand Antminer S21 XP machines and advertises deployment through hosting facilities in Paraguay and Texas. For miners able to secure comparatively cheaper electricity, buying used hardware can be a lower-cost alternative to purchasing brand-new machines—while still bringing meaningful hashpower to the network.
That said, BlocksBridge also flags an important uncertainty: it is unclear how much of the secondhand equipment supply actually originates with publicly traded miners, and—equally important—how much of that inventory is genuinely being brought back online for Bitcoin mining versus being repurposed elsewhere.
In other words, the hashrate recovery indicates displaced capacity has not vanished. But the full accounting of where the hardware ends up—and how quickly it returns—remains opaque from the available data.
Why rising hashrate is drawing “indirect bullish” arguments
Some industry observers are treating the continued growth in network hashpower as supportive of Bitcoin’s broader fundamentals. BlocksBridge notes that certain market watchers view rising hashrate as an “indirect bullish signal,” in part because it can reflect continued institutional investment in publicly traded mining companies.
CryptoQuant founder and CEO Ki Young Ju recently made that case on X, writing that “higher hashrate means stronger security and better fundamentals as a store of value.” The argument aligns with a widely held market premise: more hashing power generally improves the network’s resistance to attack by raising the cost and computational resources required to undermine it.
What remains to be tested is how durable this relationship is when large operators actively divert capacity to AI. The current data suggests the network can absorb those shifts without a persistent hashrate decline, but it also doesn’t remove the competitive pressure that comes with rising difficulty.
For readers tracking this theme, the key question is whether the hashrate rebound continues through the next difficulty adjustment cycle and beyond, or whether the network eventually settles at a lower equilibrium as AI conversions and re-deployments stabilize. Watching subsequent difficulty changes and additional reporting on miner hashrate distribution—especially between publicly traded operators and smaller hosting-driven players—will help clarify how permanent the current resurgence is.