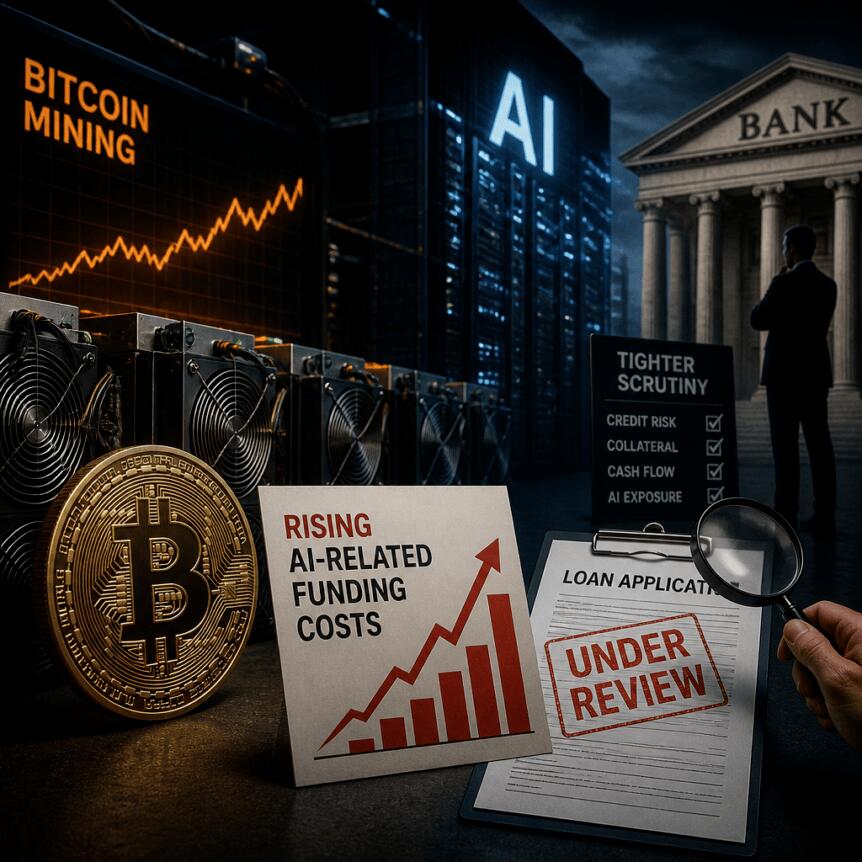
Bitcoin miners pushing deeper into artificial intelligence and high-performance computing are running into a financing reality that looks very different from their earlier playbook: lenders are increasingly selective about how data center projects are structured, funded, and de-risked.
According to a recent Miner Weekly newsletter from BlocksBridge Consulting, landing major AI customers is only one part of the equation. Miners and AI infrastructure developers still need to raise billions to buy computing hardware, build and equip facilities, and secure the power capacity required to deliver on contracted performance.
Key takeaways
- BlocksBridge says large lenders are basing data center loan approvals more on the customer, contract terms, and the “path to completion” than on the general promise of future demand.
- IREN’s reported GPU and infrastructure financing illustrates how borrowing costs can diverge sharply across different projects within the same company.
- AI-focused financing deals may include obligations beyond interest, such as backstops for lease payments that can create dilution risk through warrants.
- BlocksBridge and VanEck data point to a growing capital gap for miners’ AI infrastructure plans even as Bitcoin market conditions weaken.
Why data center lending is getting tougher
BlocksBridge Consulting frames the issue as a shift in lender behavior. While AI contracts can help justify investment, the financing process increasingly hinges on whether the borrower can prove the project can be completed on schedule and deliver reliably. In its Miner Weekly newsletter, BlocksBridge notes that “big lenders have become more selective about data center loans,” with decisions increasingly dependent on the customer, the contract, and the delivery plan.
For miners that are repurposing (or expanding) their balance sheets and operational capabilities into data centers, this means the financing challenge is not limited to interest rates. It also includes demonstrating credible development milestones, power readiness, and the commercial durability of the demand behind the build-out.
IREN’s two deals show borrowing costs can swing
The financing gap becomes easier to understand through concrete examples. The article highlights IREN, a company that has expanded from Bitcoin mining into AI infrastructure.
IREN secured a $3.65 billion GPU financing package in June at a blended interest rate of 6%. Later, in August, it arranged a separate $2.4 billion financing structure at a fixed rate of 9%. The two agreements reportedly cover different projects, making them not directly comparable on a one-to-one basis—but they still signal the variability borrowers can face even inside the same corporate umbrella.
That difference matters for investors because it affects both cost of capital and the sensitivity of financing plans to timing and project specifics. If lenders price risk differently as projects evolve—or as details about counterparties and construction pathways become clearer—the overall economics of an AI expansion can change materially.
Financing can come with lease backstops and dilution risk
The financing burden also sometimes appears in forms that extend beyond straightforward borrowing costs. In a separate transaction involving Cipher Digital, the article references a deal where Google agreed to backstop $1.4 billion in lease obligations in exchange for warrants representing 5.4% of Cipher’s equity, subject to certain adjustments.
Such structures can shift risk between parties but may introduce shareholder consequences. Exercising the warrants could dilute existing shareholders, meaning the effective “cost” of capital may be a mix of interest-like burden and ownership dilution, depending on how the warrants are handled over time.
For miners transitioning into AI, these deal mechanics underscore that lenders and strategic backers may require stronger protections as projects become more capital-intensive and operationally complex.
Capital gaps widen even during the bear market
The borrowing and deal complexity arrives as miners increasingly take on debt to fund AI expansion. The article cites VanEck data showing that, at the height of the Bitcoin bull market last October, miners’ debt surged roughly 500% from the second quarter of 2024.
But the demand for capital has not eased with weaker crypto market conditions. BlocksBridge Consulting’s June 2026 analysis—using VanEck data—suggested that publicly traded Bitcoin miners need roughly $50 billion to complete planned AI infrastructure projects. Within that estimate, it points to a $21.1 billion funding gap at IREN alone. The same analysis also attributes substantial required funding to other miners, estimating $7.2 billion for Riot Platforms and $4.6 billion for HIVE Digital.
The implication is a key asymmetry for the sector: even as Bitcoin mining economics deteriorate during bear markets, the capital requirements for AI infrastructure can keep climbing or remain urgent. That tension can put pressure on balance sheets, especially for companies whose financing terms tighten as lenders become more demanding.
Investors and operators should watch how quickly miners can convert AI customer commitments into completed, power-ready facilities—and whether lenders continue to widen the gap between projects that look “bankable” versus those that face delays, construction risk, or weaker contract economics.