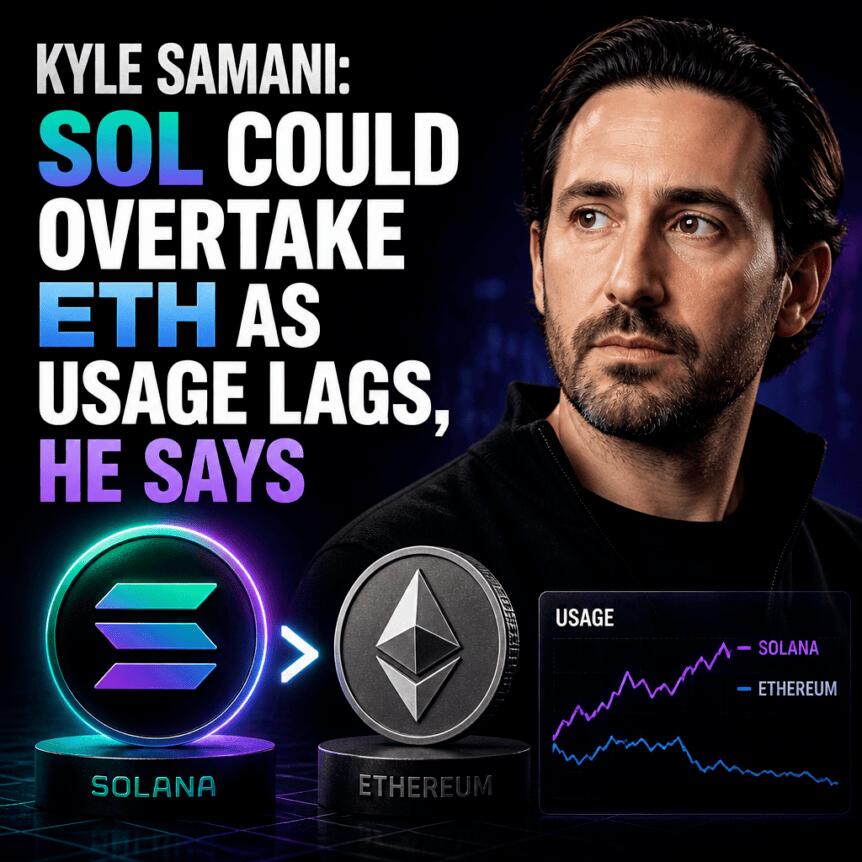
Multicoin Capital co-founder Kyle Samani believes the next phase of crypto company building could tilt further toward Solana as developers look for networks that are simpler to operate while still offering robust functionality. In a discussion with Cointelegraph, Samani argued that Solana is likely to become the “default” smart contract platform for more firms during the current market cycle, potentially eroding Ethereum’s long-held dominance in that role.
Samani’s stance is notably consistent with his track record: Multicoin accumulated an early position in Solana, and he has been one of its most persistent public advocates. His comments also come as Solana’s token has outperformed Ethereum in the recent upswing, while showing a deeper drawdown during the prior bear market—two dynamics that investors may want to reconcile when assessing the sustainability of the current momentum.
Key takeaways
- Kyle Samani predicts more crypto companies will default to building on Solana instead of Ethereum, citing operational ease and network “functionality.”
- He claims Ethereum’s value accrual is “questionable,” arguing that Ether’s largest role today is tied to stablecoins and collateralized borrowing.
- Recent market performance shows Ether up about 30% over the past month versus Solana’s roughly 34% gain, according to TradingView.
- On a longer window, TradingView data cited by Cointelegraph shows SOL down 59% over the past year versus ETH down 45%.
- DefiLlama fee data referenced in the report shows Solana collecting more monthly fees than Ethereum in the period cited, reinforcing Samani’s operational and usage argument.
Why Samani thinks Solana could replace Ethereum’s “default” status
Speaking on Cointelegraph’s “Trade Secrets,” Samani said he expects Solana to “flip” Ether during the current market cycle. His core argument is not only about technical capability, but about how easy it is for companies to consolidate their operations on a single chain.
“They’ll all switch their default over to Solana because it’s the most functional network for all of them and it’s just easier to consolidate their operations around Solana to the extent that they can.”
From an investor’s perspective, the implication is straightforward: if more new products, deployments, and enterprise-minded launches choose Solana by default, demand for Solana’s ecosystem resources could strengthen relative to Ethereum. At the same time, Samani’s framing suggests he sees network choice as something that compounds—once companies standardize on one environment, switching costs rise for the next set of funding rounds, partnerships, and product iterations.
Samani’s forecast also carries a valuation challenge. The report notes that reaching Ether’s current market cap (about $293 billion at the time of the cited discussion) would require SOL’s market capitalization to multiply roughly fivefold, with SOL referenced at about a $58 billion market cap in the underlying comparison.
Criticism of Ethereum’s value accrual
Alongside his Solana preference, Samani was sharply skeptical about Ethereum’s ability to capture and sustain economic value for token holders. He described Ethereum as a large smart contract network whose asset value accrual is, in his view, unclear or limited.
“It’s a $400 billion to $300 billion asset that has questionable value accrual, if any, and it’s not growing at all.”
Samani argued that investors may not find Ether’s valuation compelling relative to other opportunities available at what he characterized as “more reasonable prices.” He also suggested that Ethereum’s continued relevance stems primarily from stablecoins and from stablecoins or capital strategies that use Ether as collateral—rather than from broader organic adoption that, in his view, would drive stronger accrual mechanics.
Notably, this critique is paired in the report with his prediction that companies will pivot toward Solana. If investors accept the premise that “usage” and “operational convenience” are what drive product ecosystems more than abstract platform status, then Ethereum’s role could shift from default builder environment to a more specialized settlement and liquidity base—at least for certain categories of new deployments.
What the recent market and fees data suggest
The Cointelegraph report ties Samani’s thesis to performance and on-chain activity indicators. In the recent market upturn, both ETH and SOL moved higher in similar percentage ranges, but Solana’s outperformance was slightly stronger in the cited window: Ether rose about 30% over the past month, while Solana rose about 34%, according to TradingView.
The comparison becomes more nuanced when the discussion shifts from short-term rallies to the prior downturn. TradingView data cited by Cointelegraph shows SOL fell about 59% over the past year, versus ETH’s roughly 45% decline. In other words, Solana has had both larger relative losses and slightly stronger recent gains—an asymmetry that can matter to traders assessing risk, drawdown tolerance, and the likelihood of “mean reversion” versus a new regime.
Fees provide another lens. The report states that, while SOL represents less than one-fifth of Ethereum’s market capitalization, Solana has surpassed Ethereum in weekly and monthly fees. According to fee rankings from DefiLlama referenced in the article, Solana generated $23 million in fees over the past 30 days and ranked fourth in monthly fees, while Ethereum generated $12.6 million and ranked in sixth place.
For builders and investors, fee generation can be interpreted in multiple ways. It may signal more demand for blockspace and on-chain execution, but it can also reflect changes in application mix or volatility-driven usage. Still, within Samani’s broader argument—“functionality” and operational consolidation—higher fee throughput is presented as evidence that Solana can deliver measurable economic activity even while competing against Ethereum’s scale.
Samani’s shifting stance—and his continued bet on Solana
The article also revisits Samani’s relationship with the crypto industry over the past few years. In February, he said he was stepping down as managing partner of Multicoin Capital after 10 years in the industry, describing it as a “bittersweet moment.” The report notes that around that time he appeared dispirited about crypto’s broader direction and briefly deleted an X post in which he said he no longer believed in the web3 vision, arguing that crypto had become less interesting than many enthusiasts expected.
But the same report indicates that his outlook did not translate into an exit. In September, Samani joined the US board of directors at crypto trading platform Backpack, suggesting he remained engaged with the operational side of the industry rather than stepping away completely.
On Solana specifically, the report frames the bet as long-running. Samani says he entered crypto through Ethereum in 2016 and later became dissatisfied with how Ethereum developers addressed scaling issues, according to Cointelegraph’s references in the piece. He encountered Solana soon after founding Multicoin in May 2017, and Multicoin went on to lead some of Solana’s earliest investment rounds in 2018.
Multicoin’s prominence is also contextualized in the report: it cites that the firm reported managing $5.9 billion in assets in May 2025, positioning it among the most prominent crypto investment firms. The underlying message is that Samani’s current prediction isn’t coming from a standing-on-the-sidelines viewpoint—it’s tied to a sustained investment and belief structure.
The report further adds biographical context: before co-founding Multicoin, Samani co-founded Pristine, a healthcare IT company that built software for Google Glass used by surgeons.
What to watch next
Samani’s prediction hinges on whether more companies treat Solana as the default operational environment—and whether Ethereum’s value accrual narrative continues to weaken for token holders. Investors should watch for concrete signs of ecosystem consolidation on Solana, alongside continued fee and usage comparisons, to see whether this “default switch” thesis holds beyond commentary.