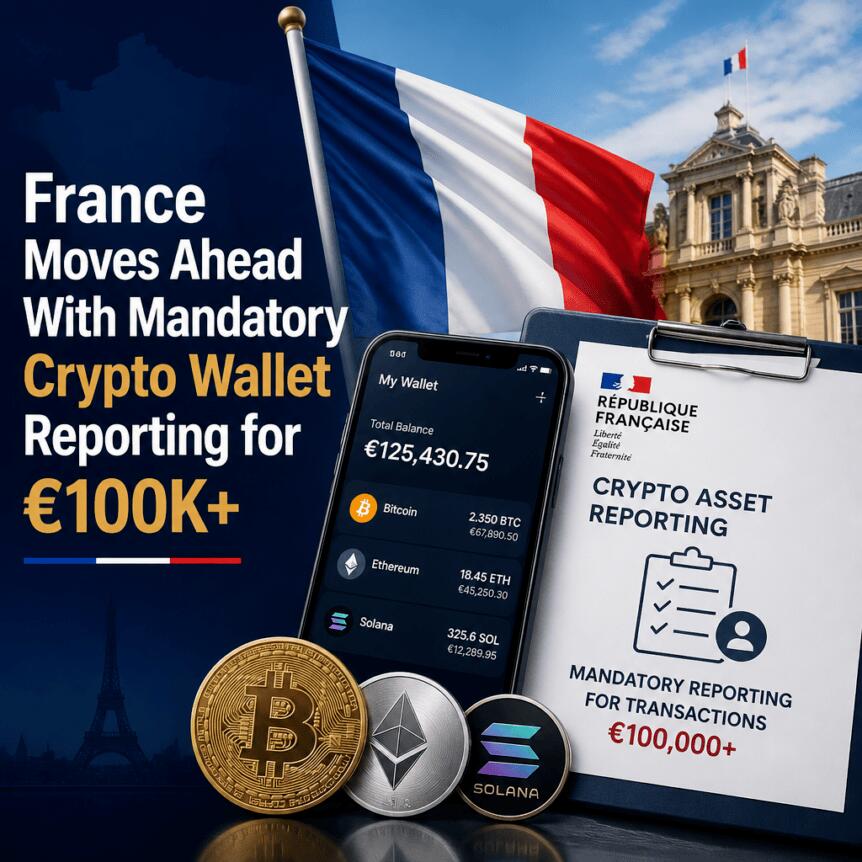
French lawmakers have moved to tighten oversight of self-custodied cryptocurrency holdings, backing an amendment that would force individuals to report crypto assets worth at least 100,000 euros or risk penalties.
The proposal—numbered I-CF821—was adopted by the National Assembly’s Finance Committee on Friday. It targets crypto held outside regulated crypto-asset service providers, including assets stored in personal wallets, and would insert new reporting obligations into France’s general tax code.
Key takeaways
- The amendment would require taxpayers to disclose self-custodied crypto holdings equal to or above 100,000 euros.
- Reporting would be based on the value of holdings as of December 31.
- Non-compliance could trigger fines up to 10,000 euros.
- The measure was adopted by the Finance Committee, but it still faces parliamentary hurdles after parts of the broader 2027 budget bill were rejected.
- France’s crypto policy push aligns with a wider effort to reduce perceived gaps between realized crypto gains and what is declared to tax authorities.
What the amendment would require
Under the amendment adopted by the Finance Committee, holders of crypto assets that are not held via a crypto-asset service provider would have to report their holdings once they reach the threshold of 100,000 euros. The scope explicitly includes cryptocurrencies held in individuals’ own custody, such as in personal wallets.
The amendment sponsors said it is meant to address tax evasion concerns. To support the policy, they pointed to a parliamentary inquiry into the taxation of wealthy individuals, which reportedly found that crypto capital gains totaled 3.5 billion euros in 2021, while only 400 million euros in crypto holdings were declared to tax authorities for that year.
In legal terms, the text would add a provision to France’s general tax code. It would require disclosure based on how much the assets are worth as of Dec. 31, and it would set a penalty framework for failures to declare—citing fines of up to 10,000 euros.
Who is behind the proposal, and how it fits the committee’s broader approach
The amendment was introduced by Charles de Courson, Jean-Pierre Bataille, and Michel Castellani, three members of France’s Liberties, Independents, Overseas and Territories (LIOT) parliamentary group.
It was one of five crypto-related amendments adopted by the Finance Committee last week. Earlier, Cointelegraph reported on other proposals under discussion in connection with France’s budgeting process, including an exit tax on cryptocurrency holdings above 800,000 euros when taxpayers move abroad, as well as changes that would end tax deferrals on conversions into fiat-backed stablecoins.
Legislative momentum is mixed after budget bill setback
Although the Finance Committee approved the crypto amendments on Friday, the broader legislative picture is not straightforward. According to reporting from French public broadcaster LCP, lawmakers rejected the revenue section of the 2027 budget bill by 31 votes to 3 after the committee’s adoption.
Lawmakers are now scheduled to begin debating the revenue section of the budget in the National Assembly on Tuesday, using the government’s original draft as the starting point. That sequence matters because the crypto amendments would need to be submitted again and approved during the parliamentary proceedings in order to become part of the final legislation, as noted by French tech publication Clubic.
In other words, adoption by a key committee is an important step, but it does not guarantee the proposal will survive the full legislative process—particularly after the rejection of part of the underlying bill.
Why self-custody is the center of this policy push
Much of the debate around crypto taxation and compliance tends to focus on the transparency (or lack of it) offered by intermediaries. The amendment’s emphasis on assets held outside crypto-asset service providers suggests lawmakers see a compliance gap when individuals retain control directly through personal wallets.
If the reporting requirement advances, it would shift the burden toward individuals to disclose holdings to tax authorities, using a valuation date fixed at Dec. 31. That design also implies that taxpayers would have to be prepared to calculate the euro value of their crypto holdings at year-end, then file declarations when holdings cross the 100,000-euro threshold.
Investors and traders with significant exposure to multiple assets in self-custody may therefore need to pay closer attention to record-keeping and valuation methodology, especially because the policy includes financial penalties for failure to declare.
For now, the key question for readers is whether the amendment clears the remaining parliamentary stages after the budget bill’s revenue section was rejected by the committee. The next developments to watch are the Tuesday debate steps in the National Assembly and whether lawmakers reintroduce and successfully incorporate the crypto reporting language into the final 2027 tax framework.