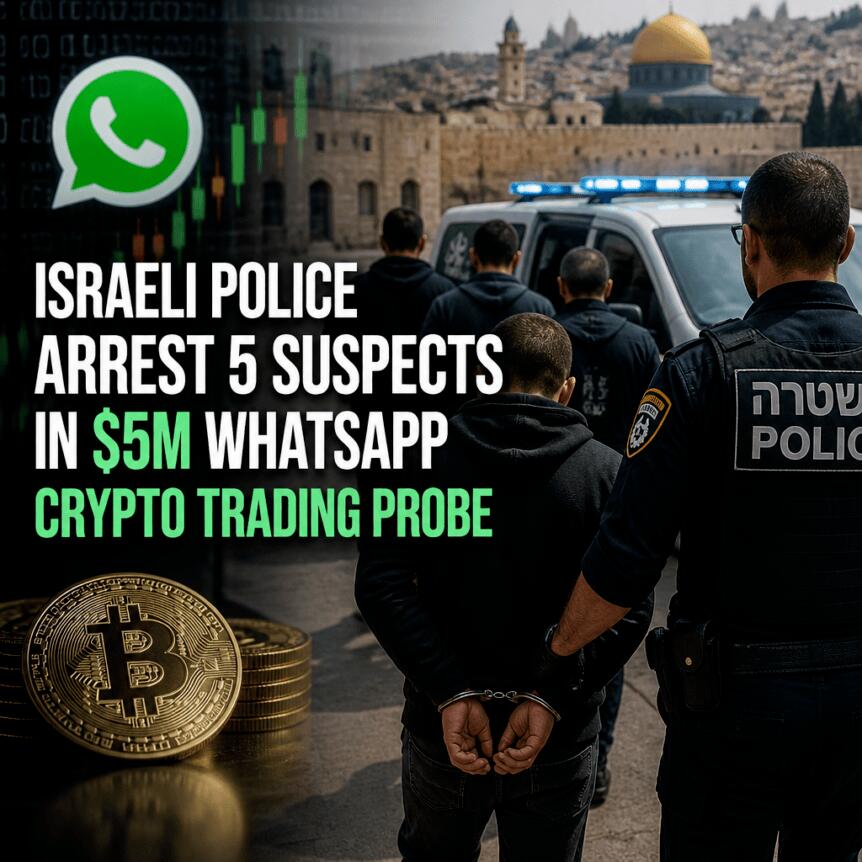
Israeli police have arrested five people in a money-laundering investigation that involved roughly 16 million shekels (about $5 million) in cryptocurrency transactions coordinated through a WhatsApp group, according to reporting by The Jerusalem Post.
Investigators from Lahav 433’s National Unit for Combating Economic Crime allege the group operated as a crypto service provider without the required license and failed to report relevant activity to Israel’s tax authorities. Police say the suspects also used fictitious agreements to make crypto proceeds transferred into bank accounts appear to be loans.
Key takeaways
- Five individuals were arrested in Israel tied to about 16 million shekels in crypto transactions allegedly arranged via a WhatsApp group.
- Authorities claim the suspects provided crypto-related services without a license and did not report transactions to Israel’s tax authority.
- Police allege fake agreements were used to disguise crypto-derived funds as “loans” in bank records.
- Searches included seizures of crypto wallets, computers, and tens of thousands of shekels in cash.
- Israel’s Tax Authority also disclosed separate arrests on Oct. 6 connected to alleged failures to report crypto activity.
WhatsApp-coordinated crypto scheme under investigation
The case centers on a WhatsApp group that, according to investigators, helped facilitate cryptocurrency transactions amounting to approximately 16 million shekels (about $5 million). Police allege the group’s members offered crypto services without authorization and that they did not disclose transactions to Israel’s tax authorities.
Beyond the alleged lack of licensing, authorities focused on how the proceeds were handled. Police allege the suspects used fictitious agreements to make transfers from crypto activity appear—on paper and through bank documentation—as loans. If proven, this would indicate not only operational non-compliance, but also an attempt to create records intended to mislead auditors and investigators.
During the probe, police seized wallets, computers, and tens of thousands of shekels in cash while searching the suspects’ homes. The five arrested people were questioned on suspicion of money laundering, fraud, and providing financial asset services without a license.
Lahav 433 targets both licensing and reporting failures
Investigators from Lahav 433’s National Unit for Combating Economic Crime described the matter as involving multiple legal breaches—criminal conduct tied to laundering and fraud, as well as regulatory and tax-related failures.
Israel’s enforcement approach, reflected across multiple cases, is not limited to tracing crypto flows. Authorities are also examining whether crypto-related services were conducted under proper authorization and whether parties met their obligations to report activity to tax authorities.
This dual focus matters for market participants because it highlights that compliance expectations extend across both the operational side (licensing/regulated activity) and the reporting side (tax disclosures for crypto trades and transfers). For traders, intermediaries, and anyone facilitating transactions, documentation and reporting practices can become as important as the underlying movement of funds.
Israel’s Tax Authority adds separate arrests over unreported crypto trades
Separately, Israel’s Tax Authority announced two additional arrests on Oct. 6 involving suspected failures to report crypto activity.
One case involved trades described by the Tax Authority as worth “tens of millions of dollars,” according to the announcement. In the other, the Tax Authority said an Ashdod resident allegedly failed to report income from about $13 million in crypto trades carried out between 2019 and 2021.
Taken together with this week’s Lahav 433 arrests, the announcements underscore a broader pattern: Israeli authorities appear to be pursuing crypto tax compliance as a core enforcement objective, not just isolated cases of fraud or laundering.
Audit findings point to a compliance gap
The enforcement drive follows findings from a November 2024 audit by Israel’s State Comptroller. That audit reportedly found that about 500 people submitted reports on crypto activity each year on average between 2018 and 2022, out of at least 200,000 potential filers.
While the arrests represent individual cases, the audit suggests a systemic issue—potentially low participation in reporting requirements relative to the size of the eligible population. That kind of mismatch often drives regulators toward investigations designed to identify non-compliance and recalibrate incentives for disclosure.
For investors and anyone holding or trading digital assets, the practical takeaway is straightforward: the gap highlighted in the audit implies that reporting rules are likely to remain a priority for Israeli enforcement efforts, especially as authorities improve their ability to connect reported activity with on-chain behavior and financial records.
What to watch next
As wallets, computers, and bank-linked documentation are analyzed, the key open questions are what evidence substantiates the alleged fictitious loan arrangements and how investigators establish the scope of “providing financial asset services” without a license. Readers should also watch for follow-on reporting and enforcement actions tied to tax disclosures, especially given the State Comptroller’s reported scale of underreporting.